Budgeting doesn’t have to be complicated, stressful, or restrictive. If tracking every single rupee or dollar feels overwhelming, the 50/30/20 budgeting rule offers an intuitive and practical framework to manage your money with clarity and confidence.
In this beginner-friendly guide, we will break down what the 50/30/20 budgeting rule is, how to calculate it with real-life examples, and actionable steps to make it work for your financial goals.
What is the 50/30/20 Budgeting Rule?
The 50/30/20 budgeting rule was popularized by Senator Elizabeth Warren and her daughter Amelia Warren Tyagi in their book All Your Worth: The Ultimate Lifetime Money Plan.
The concept is straightforward: split your after-tax (take-home) income into three clear categories:
- 50% for Needs (Essentials)
- 30% for Wants (Lifestyle & Leisure)
- 20% for Savings and Debt Repayment (Your Future)
Let’s explore each category in detail.
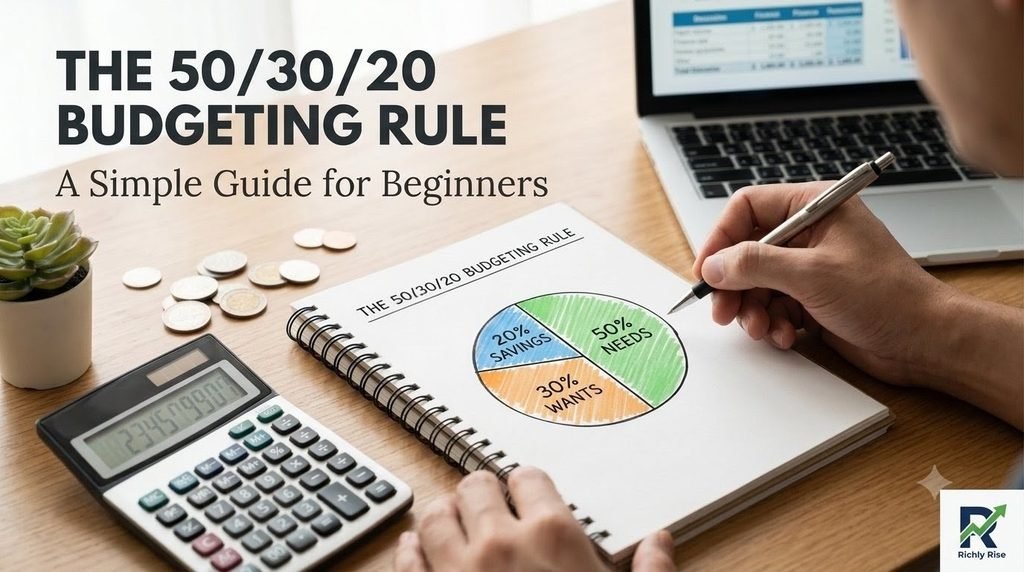
Table of Contents
1. 50% of Your Income: Needs (Essentials)
Your Needs are the non-negotiable expenses required for basic survival and daily functioning. If you lost your job tomorrow, these are the bills you would still have to pay.
Typical Examples of Needs:
- Rent or home loan EMIs
- Essential groceries and food
- Utility bills (electricity, water, cooking gas, internet)
- Basic transportation or fuel costs
- Health insurance and essential medical care
- Minimum payments on mandatory debts
Rule of Thumb: If an expense can be eliminated or postponed without severe disruption to your health or safety, it does not belong in the 50% category.
2. 30% of Your Income: Wants (Lifestyle)
Your Wants represent personal choices that enhance your quality of life. Budgeting should never feel like a punishment—allocating a healthy portion to your personal interests prevents burnout and makes your financial journey sustainable.
Common Examples of Wants:
- Dining out, café visits, and food deliveries
- Streaming subscriptions (Netflix, Spotify, Prime)
- Vacations, weekend outings, and entertainment
- Branded apparel, electronics, and lifestyle upgrades
- Hobbies and personal recreation
3. 20% of Your Income: Savings & Future Goals
The final 20% is dedicated to building wealth, creating a financial safety net, and securing long-term peace of mind. This portion belongs to your future self.
What Goes into the 20%:
- Building an emergency fund (targeting 3–6 months of living expenses)
- Systematic Investment Plans (SIPs) in mutual funds or index funds
- Retirement contributions (NPS, PPF, or 401(k))
- Extra payments towards high-interest debt clearance
Practical Example: How It Works in Real Life (50/30/20 Budgeting Rule)
Suppose your net monthly take-home salary is ₹50,000 (or $3,000):
| Category | Percentage | Amount (Example: ₹50,000) | Amount (Example: $3,000) |
|---|---|---|---|
| Needs | 50% | ₹25,000 | $1,500 |
| Wants | 30% | ₹15,000 | $900 |
| Savings | 20% | ₹10,000 | $600 |
By following this breakdown, you ensure that basic responsibilities are covered, discretionary spending remains controlled, and wealth grows consistently every month.
3 Actionable Tips to Implement the 50/30/20 Budgeting Rule Successfully
- Calculate Net Take-Home Income: Base your calculations on the exact money deposited into your bank account after taxes and statutory deductions.
- Automate Your 20% Savings: Set up auto-debits on the day following your salary credit. Paying yourself first eliminates the temptation to spend your savings.
- Be Flexible: In high-cost living areas, essentials might take up 60% of your earnings. You can adjust the ratio to 60/20/20 or 50/20/30 budgeting rule temporarily while working toward higher income or lower fixed costs.
Frequently Asked Questions (FAQ)
What if my essentials exceed 50% of my income?
Start by trimming flexible expenses within needs (e.g., renegotiating utility plans or optimizing groceries). Alternatively, reduce the ‘Wants’ category to 20% and maintain savings at 20%.
Should loan payments be counted under Needs or Savings?
Minimum required monthly payments belong under Needs. Any extra principal payments intended to eliminate debt early belong under the 20% Savings/Debt bucket.
Conclusion
The 50/30/20 budgeting rule framework is effective because of its simplicity. You don’t need complicated spreadsheets to take charge of your finances—just clarity on where your hard-earned money flows.
Start tracking your monthly expenses today, balance your three buckets, and take the next step toward financial independence. Also read: 5 Golden Rules of Personal Finance